Asset owners are repositioning for an uncertain future
Heightened geopolitical uncertainty, AI dominance and the need for diversification were defining themes at Net Zero Investor’s Transition and Climate Investment Forum, as asset owners and managers gathered in London
Opening the discussions, Lindsey Stewart, director of institutional insight at Morningstar and chair of the event, said the energy transition and physical risks remained among asset owners’ key priorities. However, he acknowledged that they were operating in an increasingly volatile and complex geopolitical environment.
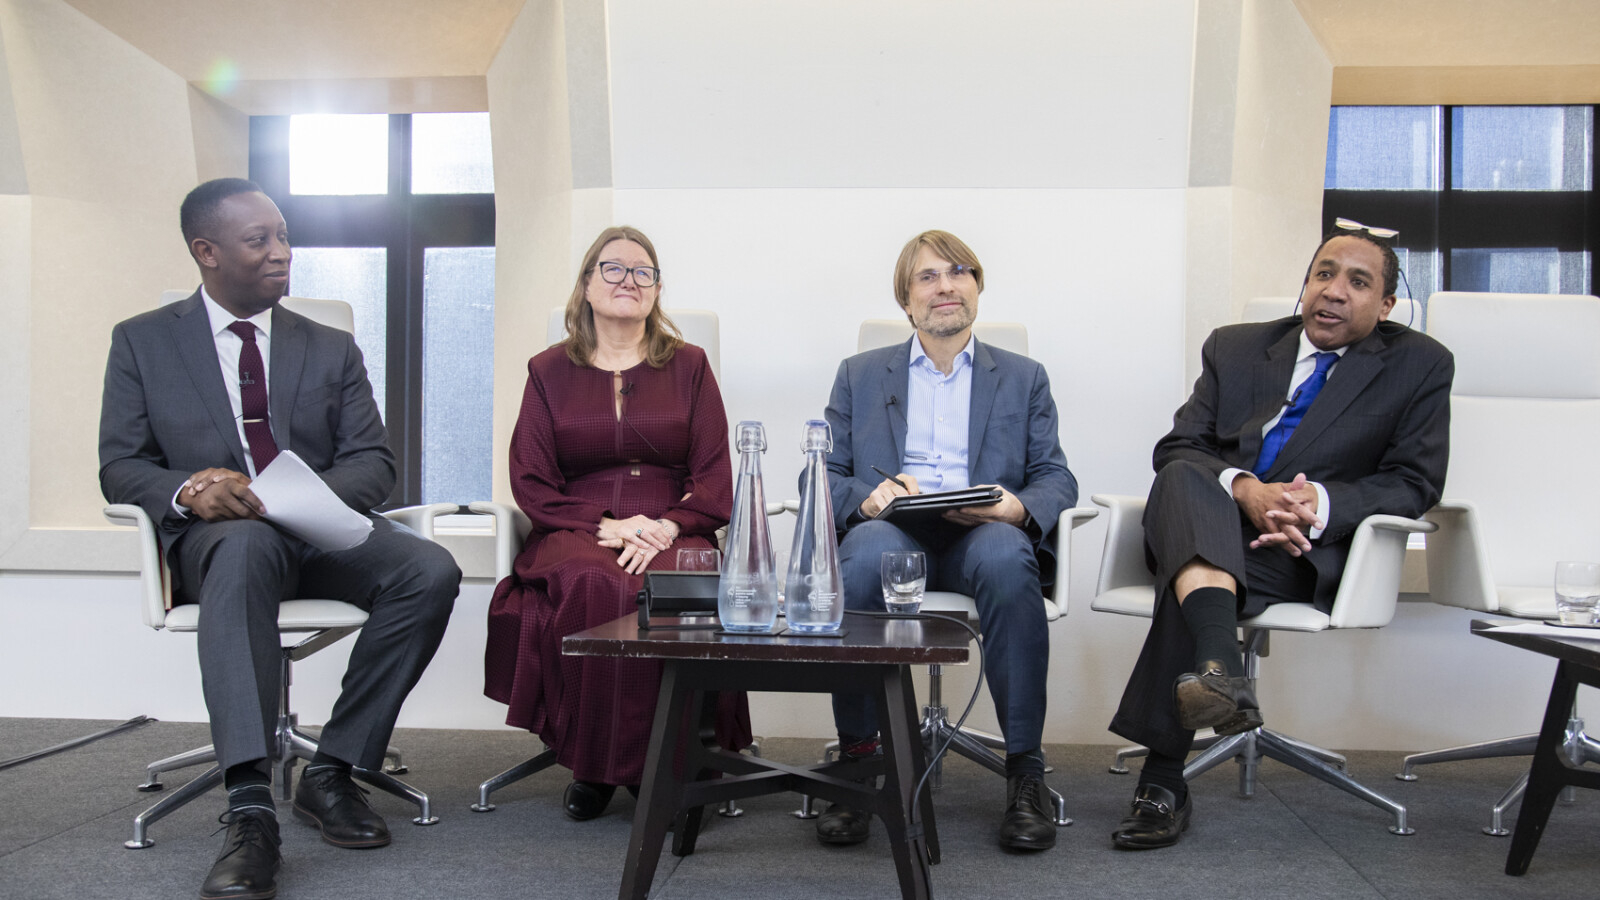
The opening panel tackled this challenge head-on, starting from the premise that asset owners face an increasingly multipolar world. Tensions are particularly tangible in the US, where climate investing has increasingly come under fire, as Gerald Chen-Young, CIO of NPPFA, the National Public Pension Fund Association, acknowledged.
Private markets and Portfolio Construction | 5 November 2026 | Central Court, London
Comparing the energy transition to historical periods of change from the movement to universal suffrage, to abolitionism, to anti-smoking, he expressed optimism that progress ultimately could not be stopped. “When it comes to the eventual transition to clean, green, prudent, profitable sustainable and renewable energy. It's just a matter of time and political will.”
Against this backdrop, AI has emerged as a defining theme, argued Mirko Cardinale, head of investment strategy at the Universities Superannuation Scheme (USS), with the capital-intensive nature of the technology triggering a repricing of the cost of capital.
This trend was reinforced by an increasingly multipolar world, in which trade wars and geopolitical conflict had added to inflationary pressures, he said. Amid this uncertainty, the focus had to be on resilience, Cardinale stressed: “You need to focus on creating a robust portfolio where a wider set of outcomes is possible. In a world of competing powers, there will be policy divergence – that is the high-level view.”
Responding to the challenge Chen-Young warned that the growing concentration risks among tech stocks posed a need for a greater focus on risks. “Imagine going to your investment committees and trying to defend an allocation decision solely on the basis of highest returns? There are other considerations that have to bear in mind as part of the articulated long-term strategy for the given pool of assets.”
Turning to the investment opportunity, Beverley Gower-Jones, founder and managing partner of the Clean Growth Fund, argued that it was time for investors to rethink portfolio diversification. “If in your listed markets portfolio you are mainly invested in Mag 7 stocks, and in your alternatives portfolio you are invested in suppliers to the Mag 7, that is not diversification.”
The alternative, she suggested, was to focus on energy as the driving force behind the AI race, with opportunities now emerging in key bottlenecks such as grid and storage capacity.
For Chen-Young, this changing environment means that a pivot is required. "If we are indeed at the end of the secular 'great moderation' era as former Fed chair Ben S Bernanke termed, we are now witnessing the dawn of a new 'great rotation', then that is a solid case for reducing allocations to listed assets and expanding commitments to real assets. Couple this with the fact that inflation is very likely not a passing fad and what results is a powerful case for 'alpha'-type allocations rather than liquid but crowded and supremely overvalued assets, generic 'beta'-types of allocations. This could be a watershed moment for institutional investment management and portfolio positioning."
Against this volatile backdrop, a key mistake investors could make was to assume that not transitioning would come without a cost, argued Nigel Topping, chair of the UK’s Climate Change Committee, which advises the government on transition planning. He urged investors in the room to hold the line on climate investing: “A bit of zigzagging is fine, but please no flip-flopping.”
The committee’s latest forecasts show that a single fossil fuel price shock would cost the UK government more than the entire transition, he said, adding that there was much to gain from adapting now. The long-term rewards would be lower borrowing costs and higher incomes, he predicted.