IEA calls for rapid development of carbon storage
Capturing carbon is a job half-done – it’s deploying safe and cost-effective storage solutions that is the real challenge.
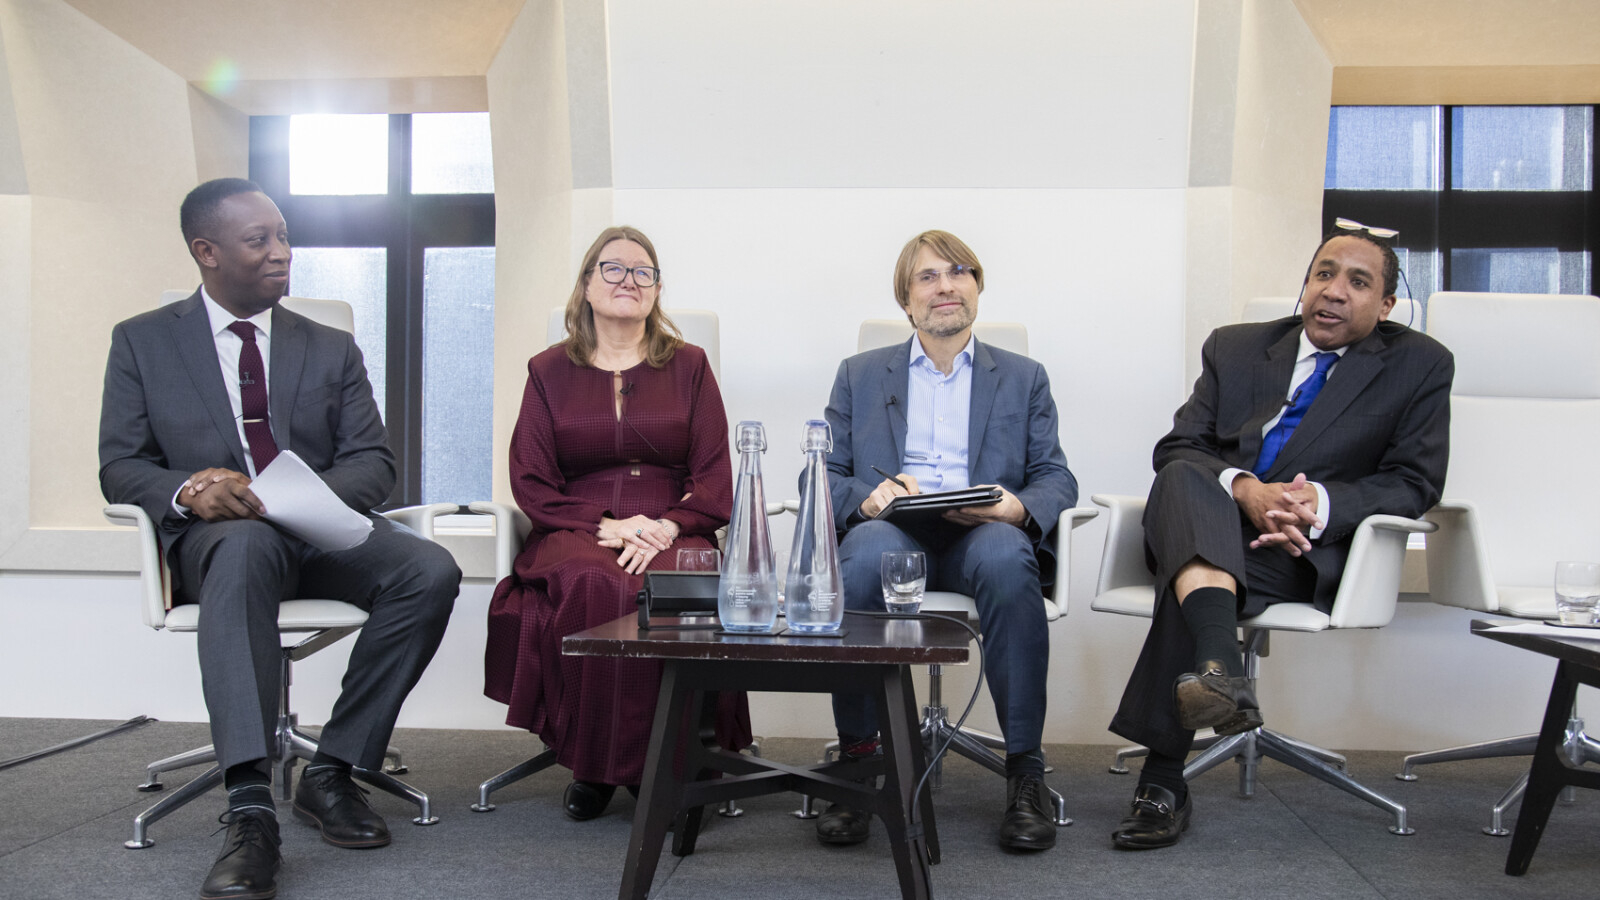
The International Energy Agency (IEA) has launched a report that examines the current state of carbon dioxide (CO2) storage solutions across the world. The report was launched as part of an IEA panel discussion where panellists emphasised the critical role of carbon storage and its pace of development in the global transition.
Timur Gül, head of the IEA’s energy technology policy division, opened the session by laying out the context of the report. Gül stressed the need to apply a dual-focus on energy security and decarbonisation. “Responses we will take today will pave the way for how we will transition to net-zero emissions and the pace at which we are able to do it … balancing energy security and climate concerns at the same time,” he said.
On the one hand, renewables and energy efficiency are often considered the first line of defence, yet for the “net” of “net-zero” to be achieved, the range of technologies needed is much broader. Carbon capture and storage (CCS) is part of this wider agenda.
The IEA’s report focuses on storage, referring to the process through which “CO2 is captured from the air or a point source such as industry and injected deep underground into a geological reservoir isolated from the atmosphere”.
There is a lot of momentum. There are more than 130 [CO2 storage] sites in development in over 20 countries.
Storage scale-up
Carbon storage plays a vital role in the IEA’s net-zero by 2050 scenario. Going over the numbers, Rachael Moore, IEA energy analyst and lead author of the report, stated that in 2050, the IEA expects 6.2 gigatonnes of CO2 to be captured annually. Ninety-five percent of that needs to be stored.
That is a significant scale-up from today’s CO2 storage sites of which there are seven. Moore said: “There is a lot of momentum. There are more than 130 sites in development in over 20 countries.”
This momentum is vital to meet future demand. Sue-Ern Tan, an expert from the Oil and Gas Climate Initiative who was speaking at the panel discussion, added: “We need to acknowledge that we are not at the scale that we need to be right now. Time is ticking along.”
This scale-up requires the development of a business model for storage, a model that has multiple moving parts. According to the IEA, site ownership preference, modes of financing and revenue models are examples of what a storage business model needs to account for.
Additionally, CCS is a technology with crucial spill overs. Its growth is interlinked with that of other transition technologies. Tan mentioned the example of hydrogen: “There is also a really important recognition now in terms of CCS kickstarting the hydrogen economy as we lead up to the need to have more hydrogen in a net-zero world.”
Public sector involvement
The complexity of the storage business model means that multiple stakeholders are likely to be involved. Moore restated the IEA’s position on state-owned enterprises (SOEs): “We see a very strong role for SOEs, especially national oil companies, in developing storage.”
Another crucial part of the puzzle is financing the growth of storage. Since much of the capital is deployed in the initial stages of site assessment, storage investment carries exploratory risks. Moore argued that this determines the type of financing instrument that is needed: “Capital typically needs to come from equity or from public loans and grants; debt finance usually is not an option.”
The implication here is that public sector capital and support is critical. Moore cited Norway’s Northern Lights project to demonstrate what this looks like.
CCS in emerging markets
Many countries look to CCS as a key tool as they try to decarbonise the hard-to-abate sectors. However, as Gül observed, “some countries are ahead of others”. Emerging markets, in particular, are lagging their advanced economy peers. Tan echoed these concerns: “We should start thinking about how to support CCS outside Europe and the US.”
During the panel discussion, audience interest in Japanese storage assets was high. Norihiko Saeki, director for CCUS policy at Japan’s Ministry of Economy, Trade and Industry, discussed Japan’s experience.
Japan has been tapping into the IEA analysis to develop a CCS roadmap to 2050. According to Saeki, the target is to store anywhere between 120 million tonnes to 240 million tonnes of CO2 by 2050. This is roughly 10% of Japan’s current emissions.
To meet these goals, the Japanese government is focusing on policy reform. “We are drafting regulatory schemes for enhancing CCS business in Japan”, said Saeki. Saeki also stated that the key feature of Japanese regulation is liability allocation: “We concentrate liability risk to the operator of the reservoir.”
The overarching message from the IEA was that there is still work to be done, and planning ahead is critical. To ensure that the transition is on track, scaling up storage facilities is vital. “As part of the IEA net-zero by 2050 scenario, 1.2bn tonnes is stored in 2030 alone. In comparison, 10m tonnes was injected at the seven dedicated storage sites in operation today”, Gül said. There is clearly, no net-zero without carbon storage.
Atharva Deshmukh is Net Zero Investor’s head of research.