BlackRock’s Muijsson on adding impact to OCIO mandates
In a bid to meet growing asset owner appetite for customisation, BlackRock plans to offer its OCIO clients greater access to impact managers. Cherry Muijsson, a CIO for BlackRock’s EMEA pensions team, explains why
Gone are the days when major institutional investors can be won over by an off-the-shelf fund offering. The world’s largest asset owners are increasingly ramping up their expectations and demanding more customised investment strategies.
While increasingly complex portfolios and heightened regulatory expectations are some of the factors feeding into this trend, so are higher standards on proxy voting, ESG disclosures and climate-risk management. For example, nearly 80% of all asset owners now consider a manager’s track record on proxy voting as part of their manager selection process, according to PRI research.
NZI Transition and Climate Investment Conference | 22 October | London | Register here
Recent examples include the Taiwan Bureau of Funds awarding a $3bn climate transition infrastructure mandate to five separate managers, or the People’s Pension shifting a £28bn portfolio from pooled funds to segregated mandates.
Crucially, there appears to be no one-size-fits-all approach to meeting climate expectations, with different investors following distinct approaches to meeting their climate ambitions; the architecture of investment mandates appears to become more and more complex.
This has sometimes been a challenge for the world’s largest asset manager, BlackRock, which has recently lost some prominent pension mandates.
At the same time, the manager holds significant weight in the rapidly growing OCIO market. In recent years, the manager has taken on the £21bn British Airways pension fund portfolio and the management of the £8.8bn Royal Mail pension plan in the UK. In 2024, it also took over the investment management for the €27bn Stichting Shell Pensioenfonds.
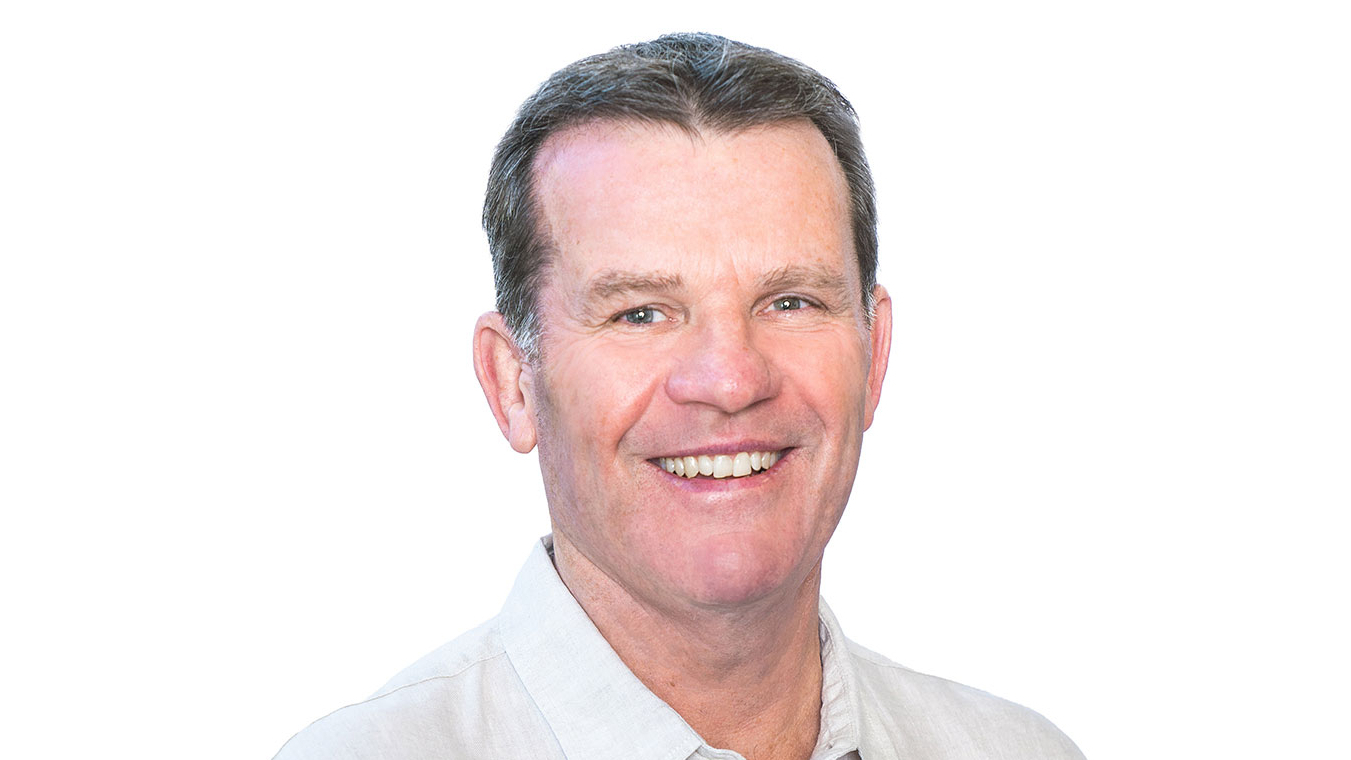
And demand for tailored allocations to impact managers is growing, explains Cherry Muijsson, a CIO for BlackRock’s EMEA pensions team within Multi-Asset Strategies and Solutions (MASS).
This summer, BlackRock announced a new strategic partnership with PCG Impact, the advisory arm of Amsterdam-founded impact investing specialist Phenix Capital Group, in a bid to help its clients with allocations to impact managers.
In practice, many of BlackRock’s clients would already have committed between 2–10% of their portfolio to impact managers.
The collaboration means that BlackRock’s OCIO clients now have access to PCG Impact’s database of some 3,000 impact managers which have already undergone a due diligence process, whilst also benefiting from PCG’s advisory and reporting capabilities, Muijsson explains.
Moreover, they now have access to more bespoke allocations. “You’re not necessarily looking for just one optimal manager or one optimal fund. You can have a combination of those.”
“You’re not necessarily bound by one strategy. You can work together to see that you can get multiple ‘flavours’ also integrated,” she adds.
Rationale for the collaboration
“The growth of impact solutions is very much rooted in what we do in our outsourced chief investment business. As a CIO, it means that I apply the same rigour to these portfolios. We really see this as a portfolio construction challenge,” she adds.
This means that rather than just focusing on financial risks and return, the manager is increasingly addressing secondary objectives set by the clients. These are often centred around climate risk management but could also be wider.
“We have some clients that have social targets around access to affordable housing, for instance. We have clients with targets around healthcare access, and clients with targets around reducing global warming.”
“One of the metrics could be the amount of renewable energy generated, so gigawatts or megawatts, that you’re generating with the financing of your projects.”
“If the client decides to focus more on investments in private equity, for instance, where it can stimulate new technologies, new climate tech, then we will also help them with what are the right targets that come into play for that,” she explains.
“What we want to achieve is when a client has decided to make an allocation, throughout the lifecycle of that allocation, they will receive these specific metrics that they’ve aligned on at the start, on a regular basis. So they can then test that secondary objective against their targets.”
Opportune timing
The timing of the new collaboration feeds into a wider overhaul of the Dutch pensions industry where major defined benefit funds have recently transitioned towards a CDC model.
The change marks one of the largest structural shifts in the European institutional market in recent history, triggering significant rethinking of current investment portfolios. A defining feature of the new model will be that funds are increasingly focused on target-date style funds with different glidepaths depending on the age of respective members,
This means that significant emphasis will be placed on the right asset allocation for specific age groups.
Many Dutch pension funds have historically had significant allocations to long-duration liability hedging in the form of LDI which may no longer make sense for younger cohorts. As a result, the risk-return dial for younger members might shift upwards, which could benefit impact allocations.
“When clients are thinking about adjusting their portfolios, they’re not necessarily just sticking with what they’re currently doing in terms of financial risk and return. There’s now that moment as well that the impact conversation can come into it,” Muijsson believes.
No trade-offs
But she is also keen to stress that higher expectations do not have to come at the expense of returns. “Typically, these clients are still looking for market-rate returns. What we are seeing, though, is that impact does not necessarily have to conflict with returns. A lot of these opportunities are already market-rate, and that’s also why that trade-off doesn’t necessarily have to be there.”
Ultimately though, BlackRock remains responsible for the OCIO portfolio, she stresses. “[This] means that any advice that we give is still coming directly from BlackRock, and this is something that’s been seen as a strength for our clients.”
“We will always be responsible for that strategic asset allocation component and really figuring out how a whole portfolio comes together. In the fund selection, BlackRock is in the lead here because we are also responsible for the financial due diligence and the operational due diligence. The impact due diligence is also sitting alongside that with the expertise from PCG.”
Three-dimensional portfolio construction
Many of BlackRock’s clients are not exactly new to impact investing, she notes. But working with an experienced impact data provider can add additional depth to portfolio management decisions, she argues.
“Rather than just asking your investment manager to think about, ‘Which asset classes do I need to get a diversified portfolio meeting my financial risk and return targets?’, it’s also around, ‘Which asset classes suit these impact objectives the best?’”
In some cases, clients may have already invested in infrastructure with a broad climate impact vision, but can now approach this in a more targeted way, she explains.
“We do have clients that have already made impact allocations, and you do see, for instance, asset classes like infrastructure being quite interesting there, whether that is transition infrastructure or whether that’s specific allocations to renewables.”
“They started with, ‘yes, we want to have infrastructure represented because we know it is something that can also be an additional diversifier in our portfolio, another source of return in our portfolio. But rather than thinking about this just on that basis, it becomes ‘can we actually do this from an impact lens?’”
This then leads to what Muijsson describes as a “three-dimensional portfolio construction challenge,” with the broad spectrum of asset classes being considered to meet a specific impact target alongside risk and return criteria.